Mastering Financial Reports
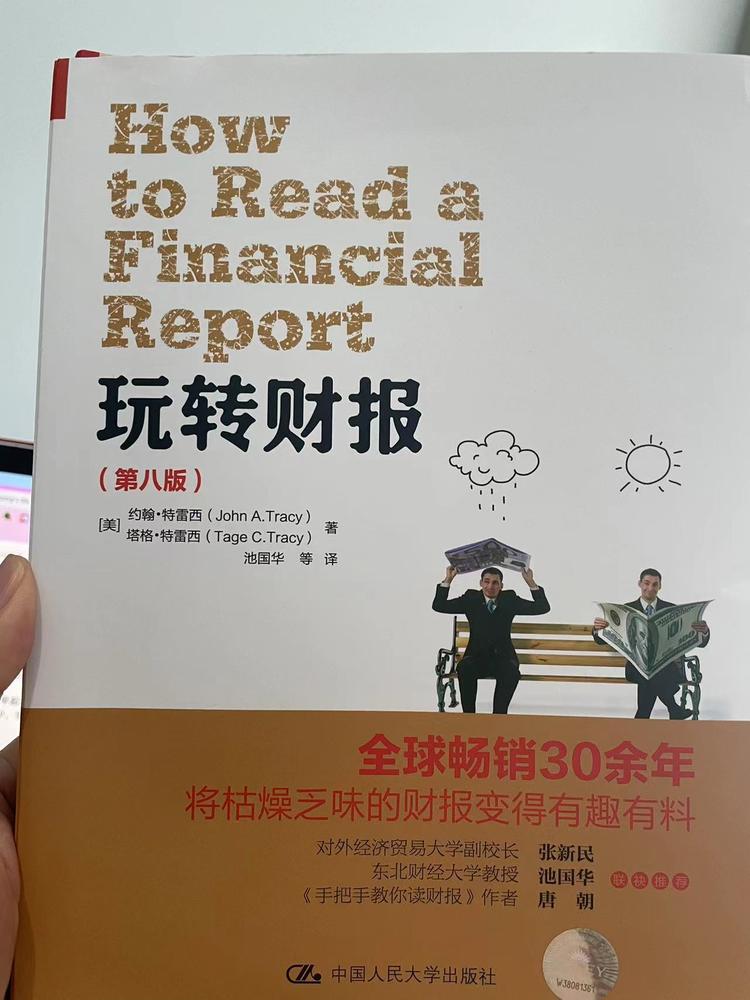
- My rating: 7 / 10
- Purchase Link
“Mastering Financial Reports” is a practical guide to help readers understand financial statements. By analyzing the three major financial statements (income statement, balance sheet, cash flow statement), it reveals how to identify a company’s true condition and competitiveness through financial reports.
Highly practical: The book provides a clear analytical framework for investors by thoroughly explaining the three major financial statements and their intrinsic connections.
Rich in Cases: Explains how to identify corporate fraud or potential risks through practical cases, with strong operational value.
- Accessible and Comprehensive: Even financial novices can quickly grasp the core points of financial statement analysis through this book.
- Multi-dimensional Perspective: Covers key business indicators of corporate operations from profitability, solvency to expansion strategies.
What I Liked 🔗︎
Some Content is More Specialized: For readers without a financial background, certain terms (such as “accrual basis”) may require additional study to fully understand.
Lack of interactivity: As a book that leans towards theory, it lacks practical exercises or tool recommendations, which may require readers to supplement hands-on experience on their own.
Accounting Entries and the Three Major Financial Statements:
A debit increases assets, a credit increases liabilities; accounting entries record a company’s financial flows, ultimately forming the income statement, balance sheet, and cash flow statement.
The income statement reflects operating results, the balance sheet reflects financial position, and the cash flow statement reflects changes in cash flow.
Core of the Income Statement:
- Accrual accounting may lead to profit manipulation, attention should be paid to gross profit margin, net profit margin, and non-operating income.
What I Disliked 🔗︎
- Profit does not equal cash flow, it is necessary to analyze the proportion of costs, taxes, and expenses by combining notes.
- Importance of the Balance Sheet:
Assets are arranged by liquidity, and liabilities are listed by urgency.
- Focus on items such as accounts receivable, inventory, accounts payable, etc., to analyze the company’s competitiveness and industry position.
- Role of the Cash Flow Statement:
Key Takeaways 🔗︎
- The net operating cash flow/core profit should be between 1.2 and 1.5 for a healthy balance.
- Cash flow cannot directly measure profit, but it can reflect a company’s liquidity.
The Interconnection of the Three Financial Statements:
- Sales revenue drives accounts receivable, while operating costs affect inventory and accounts payable.
- Net profit minus dividends equals retained earnings, but retained earnings are not a cash reserve.
Business Operating Objectives:
- Earn profits, control assets and liabilities, and secure cash flow.
- Calculate operating leverage: Companies with high fixed costs need to increase sales to reduce risk.
Evaluating Business Competitiveness:
- Gross profit margin, profit margin, supplier payment arrangement ability, and repayment arrangement ability are key indicators.
- An increase in accounts receivable or cash inflow lower than operating revenue may indicate weak repayment ability.
Corporate Expansion Strategy:
- Determine the company’s stage (expansion, maturity, or transformation) by analyzing changes in operating assets, investment assets, and financing activities.
Business Model Analysis:
- Inventory turnover rate and gross profit margin can determine whether a company competes through differentiation or scale.
Identifying Operational and Financial Risks:
- The “three-high” problem (high financial expenses, high short-term liabilities, high in a specific asset) needs to be 警惕.
- Current ratio ≥ 2, quick ratio ≥ 1, are healthy solvency indicators.
Indicators of Deteriorating Profit Quality:
- A decrease in administrative expenses, changes in accounting policies, an increase in accounts receivable, and a slower inventory turnover rate could all be warning signs.
Goodwill and Fair Value:
- Goodwill is based on fair value, and attention should be paid to its reasonableness and potential impairment risk.
Three Stages of Entrepreneurship:
- Conception (technology, users, model), Execution (product, service), Validation (performance and financial data).
Common Ratios:
- The price-to-earnings ratio is the inverse of the return on investment, and ROE > 15% can be used as a criterion for selecting high-quality companies.
Identifying Financial Reporting Traps:
- Compare with peer companies and historical data, paying attention to abnormal situations such as average salary, cash-to-short-term-debt ratio, etc.
The Importance of Footnotes:
- Footnotes in financial statements conceal important information; it is necessary to carefully read the board report and disclosures of major matters.
Three ways to make money:
- Physical arbitrage, advertising monetization, financial arbitrage (information asymmetry).
Customer value:
- The lowest total cost (time, money, emotion), optimal quality, and optimal service are key to enhancing customer value.
New articles on AI agents, full-stack engineering, and a one-person company
I email new writing about AI and agents, full-stack engineering, and building a one-person company. No spam, and you can unsubscribe anytime.